Some parts of a home sit outside the walls.
For many private clients, the spaces beyond the main house have become part of how the property is lived in, enjoyed and understood.
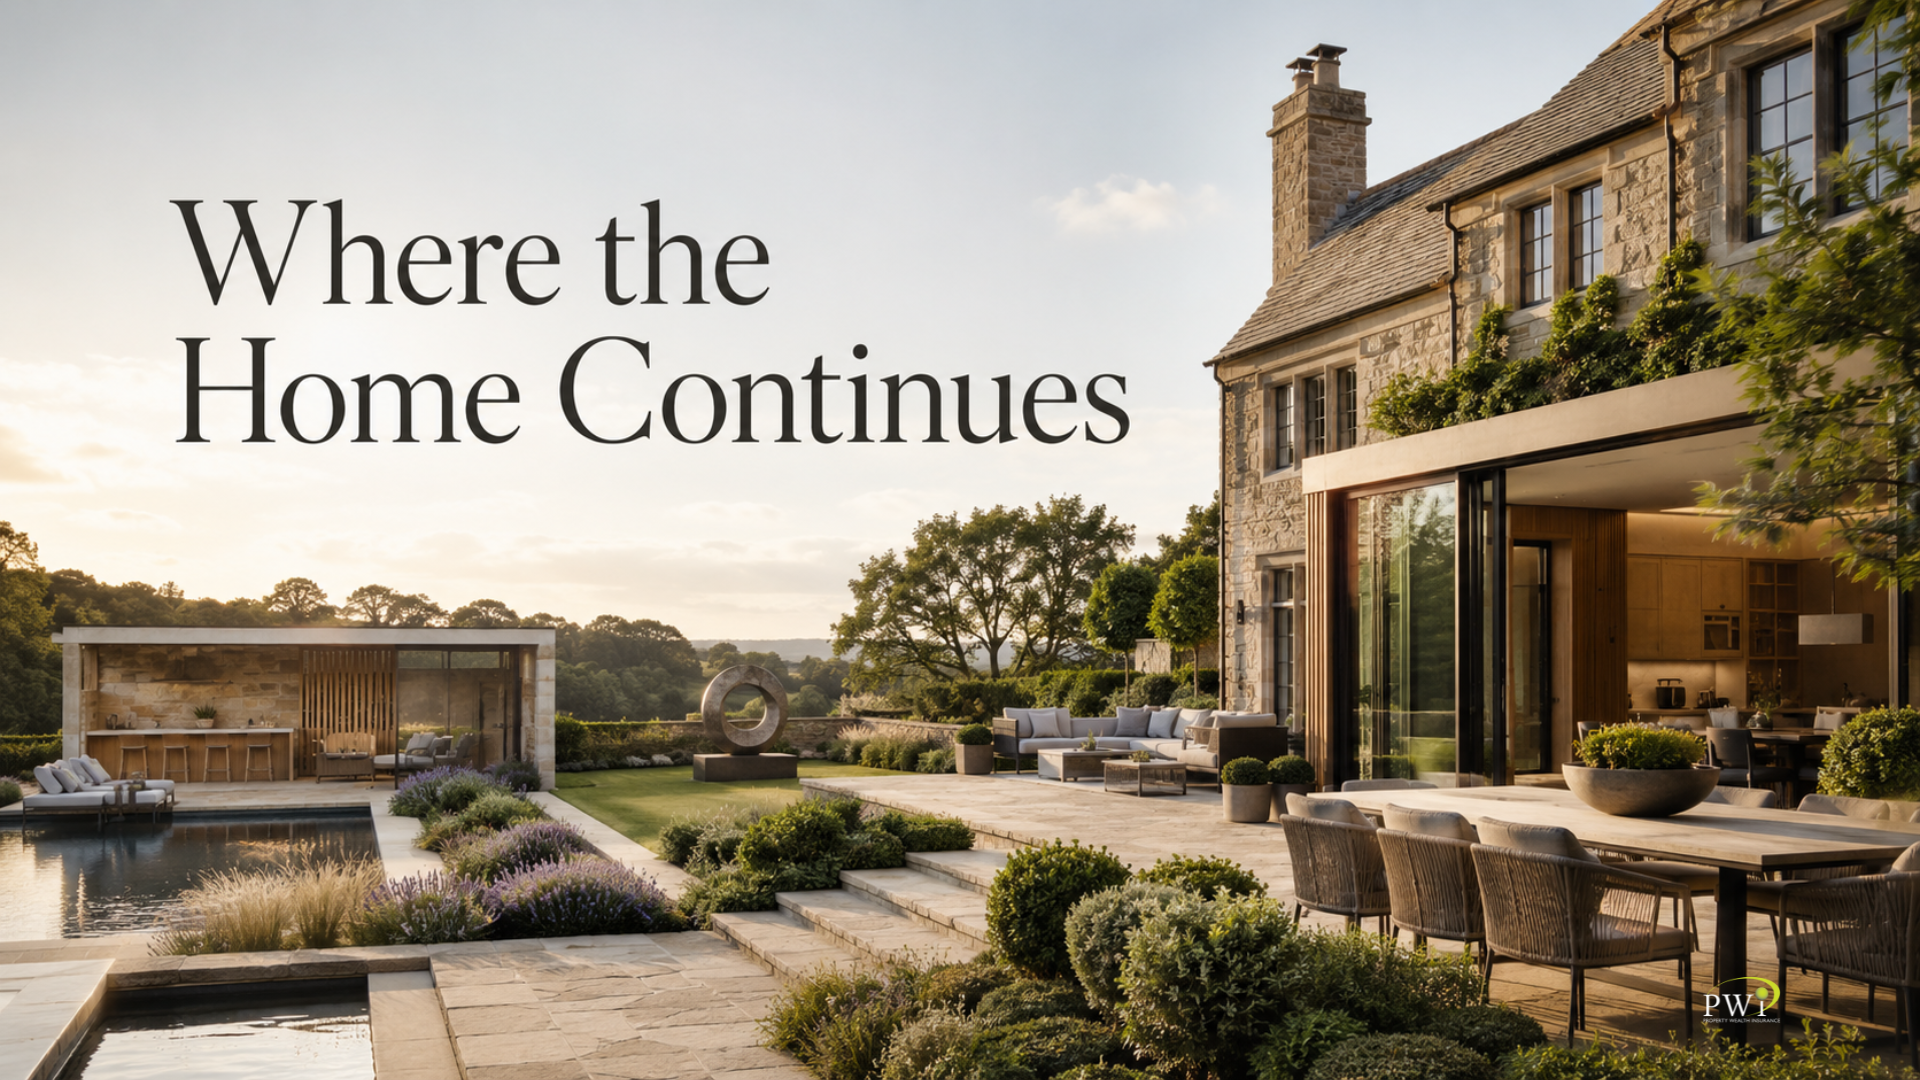
A garden room used as a studio.
An outdoor kitchen designed for summer entertaining.
A pool house, gym, workshop or guest space.
A sculpture placed carefully in the grounds.
An outbuilding storing furniture, equipment, wine, art, garden machinery or seasonal pieces that may not be thought of as “contents” in the usual sense.
None of these details are unusual in themselves.
That is often why they are missed.
Outdoor living has changed the way many substantial homes are used. The garden is no longer simply the area around the house. It may include built structures, specialist installations, lighting, heating, technology, furniture, planting, water features, artwork and spaces that are used almost as an extension of the home itself.
The question is not whether every item needs to be treated separately or turned into a list.
It is whether the whole property has been understood properly.
A standard review may naturally focus on the main building and the contents inside it. Bedrooms, kitchens, bathrooms, living spaces, jewellery, art, furniture and valuables tend to be easier to identify because they sit within the four walls of the house.
The spaces outside those walls can be less obvious.
Garden rooms may be used as offices, studios, gyms or guest accommodation. Outdoor kitchens may include specialist appliances, fitted furniture, refrigeration, heating, lighting and entertainment systems. Pool houses may hold equipment, changing areas, furniture and technology. Outbuildings may contain tools, machinery, leisure equipment or items moved from the main house for convenience.
Then there are the grounds themselves.
Landscaping, gates, boundary walls, fountains, statues, irrigation systems, terraces, pergolas and mature planting can all contribute to the character and value of a property. Some may be costly to repair or replace. Others may need specialist contractors or materials if damaged.
For private clients, this can matter because the way these spaces are used is often very personal.
A garden room may not feel like an “outbuilding” to the owner. It may feel like part of daily life.
An outdoor kitchen may not feel like a separate asset. It may simply be where the family spends summer evenings.
A sculpture in the garden may not be thought about in the same way as art inside the home, even though it may carry significant value.
These are not technicalities for the sake of it.
They are the small details that help shape a more accurate picture of the property as a whole.
The same is true when homes are used for entertaining. Guests may move through indoor and outdoor spaces. Caterers may use external kitchens. Temporary structures may be added. Garden furniture, lighting, heating and equipment may be used more heavily at certain times of year.
Most of this will feel completely normal to the homeowner.
But from an insurance perspective, normal use still needs to be understood.
For professionals who work closely with private clients, this can be a useful area to keep in mind. Wealth managers, solicitors, estate agents, family offices and property advisers may hear clients talk about landscaping projects, garden studios, pool houses, outdoor entertaining spaces or work being carried out in the grounds.
A client may not describe these things as part of their insurance arrangements.
They may simply say they have added a garden room.
Or built an outdoor kitchen.
Or installed a sculpture.
Or converted an outbuilding.
Or moved valuable items into a pool house or studio.
Those comments can be useful prompts.
Not because every detail needs to become complicated, but because the protection around the home should reflect the way the property is actually lived in.
At Property Wealth Insurance Brokers, we work with clients whose homes often have more depth than a standard property arrangement may allow for.
Our role is to help look beyond the obvious: not only the main house, but the spaces, structures, contents and features that sit around it.
A considered whole-property review can help bring those details into view, from garden rooms and outdoor kitchens to pool houses, sculptures, outbuildings and the items kept within them.
Because the home is not always contained by the walls of the house.
Sometimes, what matters most continues beyond the back door.
Property Wealth Insurance is a trading name of A-One Insurance Services (Bmth) Ltd. A-One Insurance Services (Bmth) Ltd is authorised and regulated by the Financial Conduct Authority (FCA).